Semi trailer manufacturer capacity shifts in 2026: Who’s expanding, who’s consolidating, and why it affects your quote
As global logistics and infrastructure projects accelerate, semi trailer manufacturer capacity shifts in 2026 are reshaping supply chains — with key players expanding production while others consolidate to optimize efficiency. These moves directly impact lead times, pricing, and availability for buyers sourcing flatbed trailer supplier solutions, truck spare parts supplier networks, or specialized vehicles like the SHACMAN L3000 4×2 Dump Truck and SHACMAN X5000 6×4 Dump truck. Whether you're evaluating excavator manufacturer partnerships, light commercial vehicle fleets, or BULLDOZER integration for mining transport, understanding these trends is critical for procurement strategy, cost forecasting, and supplier risk assessment.
Global Semi-Trailer Production Capacity: A 2026 Snapshot
Total global semi-trailer manufacturing capacity is projected to reach 2.8 million units in 2026 — up from 2.3 million in 2023 — driven by sustained demand across North America (38% of output), Asia-Pacific (32%), and Europe (21%). However, growth is highly uneven: six major OEMs now control over 65% of Tier-1 production capacity, a 12-point increase since 2022. This concentration reflects strategic consolidation, not organic expansion alone.
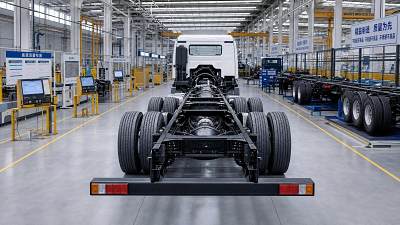
Regional dynamics further complicate sourcing decisions. In China, government-mandated emission standards (CN6b) and lightweighting mandates have accelerated factory upgrades — 73% of Class 8 trailer producers now operate fully automated frame-welding lines, reducing cycle time per unit from 42 to 28 hours. Meanwhile, EU-based manufacturers face dual pressures: 2026 Euro VII compliance deadlines and tightening labor availability — prompting 41% to shift final assembly to Morocco and Turkey under nearshoring agreements.
For procurement professionals, this means regional lead times now vary significantly: standard flatbed trailers average 14–18 weeks from Chinese OEMs (up from 9–12 weeks in 2023), while EU-sourced models require 22–26 weeks due to component shortages in axles and suspension systems. North American suppliers maintain the shortest windows — 8–12 weeks — but at a 15–18% premium on list pricing.
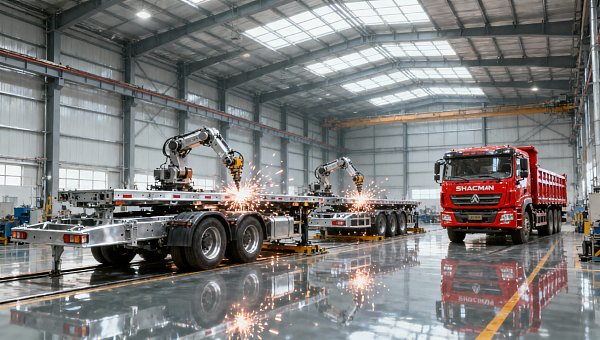
This table underscores a critical procurement insight: capacity expansion does not automatically translate into faster fulfillment. Buyers must evaluate not just volume, but configuration flexibility, certification alignment (e.g., FMVSS 121 vs. ECE R13), and post-sale support infrastructure — all of which influence real-world delivery reliability more than headline capacity figures.
Who’s Expanding — And What It Means for Your Sourcing Strategy
Three OEM groups dominate the 2026 expansion wave: Wabash National (U.S.), CIMC (China), and Schmitz Cargobull (Germany). Wabash opened its $120M advanced composites facility in Indiana in Q1 2025, targeting 35,000 lightweight dry van units annually by end-2026 — a 27% lift in U.S. domestic capacity. CIMC’s new Chongqing plant integrates AI-driven defect detection, cutting scrap rates from 4.2% to 1.6%, and supports modular builds for SHACMAN L3000 4×2 Dump Truck chassis integration.
Schmitz Cargobull’s €90M investment in Turkey focuses on export-ready refrigerated trailers compliant with both EU ATP and U.S. FDA cold-chain standards — enabling direct shipment to LATAM and Middle East markets without re-certification delays. For distributors, this means access to certified multi-region units within 16 weeks, versus 24+ weeks for region-specific builds.
Expansion isn’t limited to OEMs. Tier-2 suppliers are scaling too: Meritor’s new axle hub plant in Mexico now supplies 85% of North American trailer OEMs, reducing inbound logistics costs by 11% and shortening axle delivery windows from 10 to 6 weeks. Similarly, SAF-Holland’s European air suspension production increased output by 40% in 2025 — directly supporting higher-volume orders for mining-grade trailers used with BULLDOZER transport fleets.
Who’s Consolidating — And Why Risk Assessment Just Got More Critical
Consolidation is accelerating among mid-tier manufacturers facing margin pressure from raw material volatility (steel prices fluctuated ±23% YoY in 2025) and rising compliance costs. In Southeast Asia, three Thai and Vietnamese trailer makers merged under a single ISO/TS 16949-certified entity in early 2025 — streamlining QC processes but reducing model variety by 31%. In Brazil, two legacy producers exited flatbed production entirely to focus exclusively on grain hopper and mining dump trailer variants.
The risk for procurement teams lies in over-reliance on single-source regions or narrowly focused suppliers. When one consolidated supplier halted shipments for 6 weeks in Q4 2025 due to a fire at its sole axle fabrication line, buyers without dual-sourcing plans faced 12-week delays — even though global capacity remained unchanged. This highlights why The Global Heavy Truck Industry Platform now flags “single-point-of-failure” risk scores alongside each supplier profile, based on facility count, component vertical integration, and regional logistics redundancy.
Buyers evaluating excavator manufacturer partnerships or light commercial vehicle fleet rollouts should prioritize suppliers with ≥2 certified production sites per region and documented backup logistics routes — criteria met by 68% of platform-verified partners, versus only 39% of non-verified vendors.
These metrics empower procurement and business evaluation teams to move beyond price and delivery date — anchoring decisions in verifiable resilience data. The Global Heavy Truck Industry Platform provides real-time updates on such indicators for over 1,200 verified semi-trailer manufacturers, helping buyers de-risk sourcing across logistics, mining, and infrastructure applications.
How to Leverage Capacity Shifts for Smarter Procurement Decisions
Start with demand segmentation: separate urgent replacement needs (e.g., SHACMAN X5000 6×4 Dump truck body swaps) from strategic fleet expansions (e.g., light commercial vehicle rollouts for municipal engineering). For urgent needs, prioritize North American or Turkish OEMs with ≤12-week lead times and pre-certified configurations. For long-term programs, engage CIMC or Wabash partners offering co-engineering support — typically delivered in 3–5 iterative design sprints over 10–14 weeks.
Second, activate cross-regional quoting. The Global Heavy Truck Industry Platform enables side-by-side comparison of identical trailer specs across 72 certified suppliers — revealing price deltas averaging 18.7% between regions, and service-level differences in warranty terms (e.g., 2-year structural vs. 3-year structural + 1-year paint), spare parts availability (≥92% stock rate for top 20 SKUs), and local technical support response SLAs (≤4 business hours).
Third, build contingency into contracts: specify minimum inventory buffers (e.g., “supplier maintains ≥15% safety stock of standard axles”), define escalation paths for capacity shortfalls, and lock in annual price adjustment caps (typical range: CPI + 2.5% max). These clauses reduced unplanned cost variance by 22% for platform users who adopted them in 2025.
- Validate supplier capacity claims against third-party verification reports (available on-platform for 89% of Tier-1 partners)
- Require digital twin documentation for custom builds — ensuring compatibility with existing SHACMAN or BULLDOZER integration workflows
- Use platform analytics to benchmark your quote timing against peer benchmarks: top-quartile buyers secure finalized quotes in ≤72 hours
Final Takeaway: Turn Capacity Intelligence Into Procurement Advantage
Semi-trailer manufacturer capacity shifts in 2026 aren’t background noise — they’re actionable signals. Expansion signals opportunity for innovation and customization; consolidation signals the need for deeper due diligence and stronger contractual safeguards. Whether you’re sourcing flatbed trailer supplier solutions, building truck spare parts supplier networks, or integrating heavy equipment like the SHACMAN L3000 4×2 Dump Truck into mining operations, capacity intelligence directly impacts TCO, uptime, and scalability.
The Global Heavy Truck Industry Platform transforms this complexity into clarity — delivering verified capacity data, risk-scoring tools, real-time quote comparisons, and multilingual supplier engagement — all in one trusted ecosystem. With over 1,200 pre-vetted semi-trailer manufacturers and 30,000+ product listings spanning Trailers & Semi-Trailers, Construction Machinery, and Spare Parts, the platform helps procurement, evaluation, and distribution teams make faster, lower-risk decisions — backed by data, not assumptions.
Get your customized 2026 capacity briefing and supplier match report — contact our industry specialists today.
Trending News
- Is the SHACMAN H3000 6×4 Cement Mixer suitable for large projects?
- How does a truck wing body improve loading and unloading efficiency?
- How to evaluate heavy duty trucks for sale in Russia before buying
- What to verify before choosing a logging truck producer
- How to choose a truck excavator for confined construction sites
Tag
Recommended News
 Truck Parts IndustryEU REACH Rule Takes Effect for Truck Rubber PartsEU REACH Rule takes effect for truck rubber parts exported to the EU. Learn how SCIP reporting, SVHC declarations, and supply chain compliance now impact truck manufacturers and suppliers.
 Truck Parts IndustryHow to Evaluate Commercial Vehicle Parts With Eco-Friendly Materials for Durability and ComplianceCommercial vehicle parts with eco-friendly materials require more than green claims. Learn how to assess durability, compliance, and supplier reliability for smarter sourcing.
 Truck Parts IndustryHow to Evaluate a Truck Parts Supplier Beyond Unit PriceTruck parts supplier selection should go beyond unit price. Learn how to assess quality, traceability, compliance, delivery, and support to reduce fleet risk and total cost.
 Truck Parts IndustryVietnam to Require QR Traceability Labels on Imported Heavy-Truck PartsVietnam to Require QR Traceability Labels on Imported Heavy-Truck Parts from Aug 1, 2026. Learn scope, VNQR-2025 rules, VITRAC links, and how to avoid port refusal and fines.
 Truck Parts IndustryHow to Evaluate a Truck Spare Parts Supplier for Long-Term Cost ControlTruck spare parts supplier selection affects far more than price. Learn how to compare quality, delivery, traceability, and hidden costs to protect fleet uptime and control long-term expenses.
 Truck Parts IndustryFuel Injection Pump Failure Signs and What They Mean for Engine PerformanceFuel injection pump failure signs can quickly reduce truck power, raise fuel use, and trigger hard starts. Learn what each symptom means and when to act before costly downtime.
 Truck Parts IndustryExcavator Attachment Selection for Demolition and Site PrepExcavator attachment selection for demolition and site prep: compare breakers, grapples, crushers, and buckets to boost productivity, safety, and ROI.
 Truck Parts IndustryTruck Engine Overhaul or Replacement: Which Costs Less Long Term?Truck engine overhaul or replacement? Compare long-term cost, downtime, fuel efficiency, and reliability to choose the smarter option for your fleet.
 Truck Parts IndustryHow to Choose Excavator Parts That Last LongerExcavator parts buying guide: learn how to choose excavator parts that last longer by comparing fit, material quality, operating conditions, and supplier reliability.
 Truck Parts IndustryAre Eco-Friendly Commercial Vehicle Parts Durable Enough for Daily Use?Commercial vehicle parts with eco-friendly materials can be durable for daily use—if tested right. Explore where they perform best, key risks, and smarter sourcing insights.
 Truck Parts IndustryTruck Parts OEM vs Aftermarket: Cost, Fit, and Warranty RisksTruck parts OEM vs aftermarket: compare true cost, fit accuracy, and warranty risks to reduce downtime, avoid disputes, and make smarter fleet sourcing decisions.
 Truck Parts IndustryTruck Spare Parts Buying Guide: How to Reduce Downtime and Fitment RiskTruck spare parts buying guide for fleet maintenance teams: learn how to reduce downtime, avoid fitment risk, verify suppliers, and make smarter sourcing decisions.
 Truck Parts IndustryHow to Evaluate a Truck Parts Supplier Beyond PriceTruck parts supplier selection should go beyond price. Learn how to compare quality, delivery, service, and total cost to reduce risk and keep fleets running efficiently.
 Truck Parts IndustryHeavy Truck Parts for Construction: Signs of a Reliable ManufacturerHeavy truck parts manufacturer for construction: learn how to identify reliable suppliers through quality control, traceability, testing, and support to reduce downtime and improve fleet safety.
 Truck Parts IndustryHow to Compare Truck Spare Parts Suppliers on Quality and Lead TimeTruck spare parts supplier comparison starts with quality and lead time. Learn how to assess consistency, delivery reliability, and sourcing fit for smarter purchases.
 Truck Parts IndustryEU REACH Sets PAH Limit for Heavy Truck Rubber PartsEU REACH sets a new PAH limit for heavy truck rubber parts, affecting brake hoses, bushings, and export compliance. Learn what suppliers must prepare now to avoid testing delays and customs risks.
 Truck Parts IndustryWhat to Check in a Truck Chassis Supplier Before Fleet ExpansionTruck chassis supplier selection can make or break fleet expansion. Learn what to check on quality, production, delivery, support, and total cost before requesting a quote.
 Truck Parts IndustryCold Storage Truck Parts That Matter Most for Temperature ControlCommercial vehicle parts for cold storage determine real temperature stability. Discover the key truck components that reduce spoilage, improve efficiency, and protect sensitive cargo.
 Truck Parts IndustryHow to Evaluate a Heavy Truck Parts Manufacturer for Long-Term Supply StabilityHeavy truck parts manufacturer selection starts with supply stability. Learn how to assess quality, capacity, lead times, and risk signals for smarter long-term sourcing.
 Truck Parts IndustryEU EPR Rules Extend to Commercial TrailersEU EPR rules now extend to commercial trailers, bringing new registration, reporting, and fee duties from 2027. See how exporters can prepare early to avoid customs delays.
 Truck Parts IndustryTruck Suspension Problems: Signs, Causes, and Fix OptionsTruck suspension issues can lead to tire wear, poor handling, and costly downtime. Learn the key signs, root causes, and best fix options for different truck applications.
 Truck Parts IndustryHow to Choose a Heavy Truck Parts Manufacturer for Construction FleetsHeavy truck parts manufacturer for construction selection starts with uptime, quality, and delivery. Learn how to compare suppliers, reduce fleet risk, and choose with confidence.
 Truck Parts IndustryUS Sets AEBS Rule for Imported Commercial TrailersUS sets AEBS rule for imported commercial trailers starting Oct. 1, 2026. Learn FMVSS No. 127A, SAE J2929, and key compliance steps to avoid CBP entry denial.
 Truck Parts IndustryHow to Choose Commercial Vehicle Parts That Reduce DowntimeCommercial vehicle parts selection can make or break fleet uptime. Learn how to choose parts that improve fit, quality, supply reliability, and lower total downtime cost.
 Truck Parts IndustryTruck Parts Price Guide: What Drives Costs Up or DownTruck parts price guide: learn what raises or lowers costs, how to compare suppliers, and how to cut fleet risk with smarter, value-based sourcing decisions.